




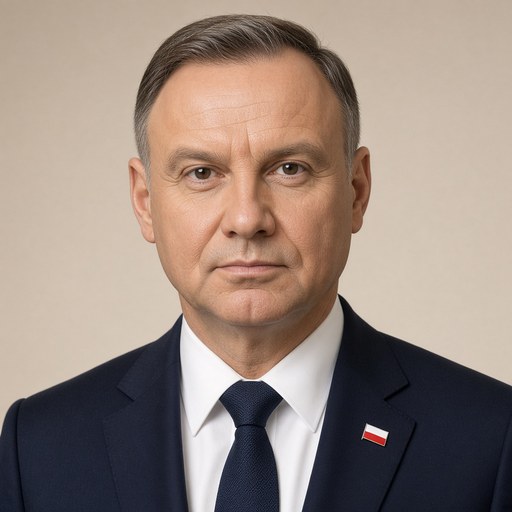
Speech during the signing ceremony of the law on credit holidays.
 Andrzej Duda · President of Poland
- Context
- Duda addressed ministers and guests at the signing ceremony of Poland's credit holiday law on July 14, 2022, providing mortgage relief to borrowers amid rising inflation.
- Main themes
- Mortgage credit holidays, borrower assistance, rising interest rates, inflation relief, anti-inflation shield extension, Polish zloty mortgage loans, household financial hardship, banking sector regulation, EU financial legislation implementation, loan repayment suspension mechanism
- Duration
- ~13 min
- Words
- 1,537
- Sentences
- 68
- Readability
- 46
- Grade
- 12.4
- Syntax
- 3.22
- Vocabulary
- 2.05
Translated from Polish
The broad sphere of national life a sentence belongs to. Every sentence has an Arena, so it is the denominator the other indices are read against.
Other68 sentences in 23 paragraphs
Esteemed Minister, Esteemed Minister, Honorable Ministers, All Distinguished Guests, Ladies and Gentlemen,
A very important moment. This was not an easy law. I would like to thank you, Madam Minister of Finance, and I would like to thank you, Mr. Minister.
Please convey my thanks to Prime Minister Mateusz Morawiecki. I also ask you to convey my thanks when you are back in parliament.
The law is not easy because, in difficult times, decisive decisions had to be made regarding the broadly understood financial market, regarding the functioning of banks, but in an extremely important context, which is primarily the daily functioning of our households. The law on community financing of economic ventures, but – above all from the perspective of Polish families – on assistance to borrowers.
It concerns all those who bought properties, who bought apartments, who built houses, in short, those who took out mortgage loans for this purpose, and today – in a situation of rising interest rates, in a situation of unfortunately high inflation that we are facing – are very often in a difficult situation. They are often also in a situation where it is hard for them to find their way.
Of course, the law has sparked much discussion, has raised controversies both in the banking environment and in the parliamentary environment, but I want to strongly emphasize that this very necessary – in my opinion – government project found support from an absolutely decisive majority. It was almost unanimously passed in parliament, it was adopted by the Sejm.
This is very important information. It shows that there was generally agreement that such a solution is needed.
What does it provide? It provides primarily what I mentioned. Above all, aside from other aspects, there is, of course, the implementation of European Union legal acts concerning various financial market institutions and various financial market mechanisms. Of course, the law also contains a very important element, which is the extension of the anti-inflation shield until October 31 of this year. This is extremely important, as it concerns actions aimed at reducing fuel prices. At this time, especially during the holiday travel season, this is a crucial element for Polish families.
But ladies and gentlemen, primarily, and most importantly, it introduces the mentioned mortgage holidays, as we say, that is, the possibility of suspending the repayment of mortgage loans.
However: attention! This applies only to mortgage loans. I want to emphasize this very strongly: it applies only to loans granted in Polish zloty, that is, it does not apply to denominated loans, it does not apply to loans indexed to foreign currency, it applies only to loans granted in Polish currency.
The mechanism is as follows: from August 1 to the end of August, and then from September 1 to the end of September, there is the first two-month period when one can obtain this temporary suspension of mortgage loan repayments, and then from October 1 to the end of the year for another two months, that is, until the end of December, one can obtain the second two-month suspension period applicable in this half of the year 2022, that is, from August 1 to the end of September and from October 1 to the end of December. And then in the following year, in 2023, such a possibility for individual consumers, for individual borrowers who have, I repeat, only mortgage loans, will be possible once a quarter. This is the solution that has been proposed.
What does this mean in practice? It means a temporary possibility of not repaying, that is, as if deferring the repayment primarily of capital installments, but also of interest, and thus the whole amount. The only element excluded from this is the loan insurance, which – after all – must be paid; the costs of loan insurance must be covered by the borrowers. However, both the capital installment and the interest portion of the installment can be suspended, that is, the repayment can be suspended for the period specified by the law – which of course does not mean complete exemption from loan repayment, so that no one, ladies and gentlemen, confuses this.
This means that it will be necessary to repay these loan installments, only they will have to be repaid later. In fact, it is a deferred payment.
But what is important? That in the current difficult situation for many families, for many people, this suspension of loan repayments provides the opportunity to make certain financial decisions, asset decisions, regarding financial management in the family or regarding daily functioning, carrying out certain ventures. You know how it can be, so this possibility for those who are interested, who want to take advantage of this suspension of mortgage repayments, will be available. This is an important element, many people are very much waiting for this.
Thank you once again, Madam Minister, Mr. Minister, and the government for preparing this solution, and I thank the parliament for its adoption.
This is, ladies and gentlemen, the most important element. Of course, for institutions operating in the housing market, in the housing construction market – this law also concerns loans granted by the Bank Gospodarstwa Krajowego, but I repeat – for institutions, I am thinking here of social housing cooperatives, for example, housing cooperatives. A similar mechanism is being introduced there to allow for the suspension of installment repayments. But – as I said – not for individual consumers, not for individual apartment owners, but for institutions that deal with construction, that deal with developing the housing market.
Ladies and gentlemen, this is the most crucial issue also in the law on assistance for borrowers. Changes have been introduced to clarify, but I repeat – the two most important elements from the perspective of the current situation, the situation of households, our situation, the situation of families, are the possibility of suspending the repayment of mortgage loans for the periods indicated in the law, first of all, and secondly, the extension of the anti-inflation shield until October 31 of this year in accordance with the law. These reliefs in the current difficult situation, which can be introduced by the government, have been introduced.
Why, ladies and gentlemen, is this decision to sign this law so quick, so swift? The law was passed on July 7 by parliament, literally – one could say – in the last hours, and is being signed today, July 14. The period for the provisions of the law to come into force from its announcement is 14 days, the so-called vacatio legis. Why such a quick deadline? Because, ladies and gentlemen, it is easy to calculate. I simply wanted this law to come into effect before the end of this month, that is, before, in short, the beginning of August. Why? Because it allows all mortgage holders whose next installment due date will be in August, starting from August 1 to the end of the month, to apply earlier, before that due date, which is necessary, in order to be able to take advantage of this suspension of loan repayment.
So the law will come into effect this month. Still in July, and during these literally last days of July, there will be the possibility to submit an application for the suspension of loan repayment, for these so-called mortgage holidays. This can be done in various ways, but among other things, there will also be a guaranteed possibility through online banking. Here, ladies and gentlemen, I want to strongly appeal to the institutions supervising the financial market, the banking market, including the Financial Ombudsman, to pay attention to how, primarily through banks, through financial institutions of the financial market, this law is being implemented. It is about ensuring that all mortgage borrowers who want to take advantage of the benefits that this law provides, the specific reliefs that this law provides, can actually do so in a timely manner, that they can effectively submit these applications, that these possibilities, also through certain systemic actions of financial institutions, banks, are guaranteed to them.
I kindly ask that the financial market supervisory institutions, the financial ombudsman, ensure this possibility. I appeal for this and I expect that for consumers, for borrowers, this element will be monitored.
Ladies and gentlemen, that is all, and once again I thank the Ministers, I thank the Government. I am glad that this law could be signed so quickly and that it can be implemented so quickly. It is indeed needed today. It is a breath of fresh air for those who have these mortgage loans, and that is very many families in Poland who are repaying loans for the apartments in which they live, for the houses.
Once again, I want to emphasize, only loans granted in Polish zloty and, ladies and gentlemen, only for one apartment or one house, that is, the one that is actually used by the consumer, by the family for residential purposes. If someone has five residential units, for example, and five loans, they will only be able to receive such a waiver for one, as we assume, of course, that they are using only one.
Ladies and gentlemen, that is all. Thank you once again.
The original Polish. The tags above are read on the English translation's sentences.
Wielce Szanowna Pani Minister, Wielce Szanowny Panie Ministrze, Szanowni Państwo Ministrowie, Wszyscy Przybyli Goście, Szanowni Państwo,
Bardzo ważny moment. To nie była łatwa ustawa. Bardzo dziękuję za to Pani Minister Finansów, bardzo dziękuję za to Panu Ministrowi.
Proszę, żeby przekazać moje podziękowania na ręce Pana Premiera Mateusza Morawieckiego. Proszę także, żeby przekazać moje podziękowania, kiedy będą Państwo ponownie w parlamencie.
Ustawa niełatwa, dlatego, że w trudnych czasach trzeba było podjąć zdecydowane decyzje dotyczące szeroko pojętego rynku finansowego, dotyczące funkcjonowania banków, ale w kontekście niezwykle istotnym, jakim jest przede wszystkim codzienne funkcjonowanie naszych gospodarstw domowych. Ustawa o społecznościowym finansowaniu przedsięwzięć gospodarczych, ale – przede wszystkim z punktu widzenia polskich rodzin – o pomocy kredytobiorcom.
Chodzi o wszystkich tych, którzy kupili nieruchomości, którzy kupili mieszkania, którzy zbudowali domy, krótko mówiąc, w tym celu wzięli kredyty hipoteczne, a dzisiaj – w sytuacji rosnących stóp procentowych, w sytuacji niestety dużej inflacji, z jaką mamy do czynienia – bardzo często są w trudnej sytuacji. Bardzo często są też w sytuacji, w której trudno jest im się odnaleźć.
Oczywiście, ustawa wzbudziła wiele dyskusji, wzbudziła kontrowersje i w środowisku bankowym, także w środowisku parlamentarnym, ale chcę bardzo mocno podkreślić, że ten bardzo potrzebny – w moim przekonaniu – projekt rządowy znalazł poparcie absolutnie zdecydowanej większości. Prawie jednogłośnie został przegłosowany w parlamencie, został przyjęty przez Sejm.
To jest bardzo ważna informacja. To pokazuje, że generalnie była zgoda co do tego, że tego typu rozwiązanie jest potrzebne.
Co ono daje? Daje przede wszystkim to, o czym wspomniałem. Przede wszystkim, poza innymi aspektami, oczywiście następuje implementacja aktów prawnych Unii Europejskiej dotycząca różnych instytucji rynku finansowego i różnych mechanizmów rynku finansowego. Oczywiście ustawa zawiera także bardzo ważny element, jakim jest przedłużenie tarczy antyinflacyjnej do 31 października tego roku. Rzecz niezwykle istotna, bo to kwestia chociażby działań, które mają prowadzić do obniżenia cen paliw. W tej chwili, w dobie zwłaszcza wyjazdów wakacyjnych tak ważny element dla polskich rodzin.
Ale proszę Państwa, właśnie przede wszystkim, co najważniejsze wprowadza wspomniane wakacje kredytowe, jak to mówimy, czyli możliwość zawieszenia spłaty kredytów hipotecznych.
Przy czym: uwaga! Dotyczy to wyłącznie kredytów hipotecznych. Chcę to bardzo mocno podkreślić: dotyczy wyłącznie kredytów udzielonych w złotym polskim, czyli nie dotyczy kredytów denominowanych, nie dotyczy kredytów indeksowanych do waluty obcej, dotyczy wyłącznie kredytów udzielonych w walucie polskiej.
Mechanizm jest następujący: otóż od 1 sierpnia do końca sierpnia, a następnie od 1 września do końca września następuje pierwszy okres dwóch miesięcy, kiedy można uzyskać to czasowe zawieszenie spłaty kredytów hipotecznych, a następnie od 1 października do końca roku przez kolejne dwa miesiące, czyli do końca grudnia, można uzyskać drugi dwumiesięczny okres zawieszenia obowiązujący w tym półroczu 2022 roku, czyli od 1 sierpnia do końca września i od 1 października do końca grudnia. A następnie w kolejnym roku, w 2023 roku taka możliwość dla indywidualnych konsumentów, dla indywidualnych kredytobiorców, którzy mają, powtarzam, kredyty hipoteczne wyłącznie, będzie możliwa raz na kwartał. To jest to rozwiązanie, które zostało zaproponowane.
Co to w praktyce oznacza? Oznacza to czasową możliwość niespłacania, czyli jak gdyby odroczenie w czasie spłacania przede wszystkim rat kapitałowych, ale także odsetek, a więc całości. Jedyny element wyłączony z tego to ubezpieczenie kredytu, które – mimo wszystko – musi być płacone; koszty ubezpieczenia kredytów muszą być pokrywane przez kredytobiorców. Natomiast zarówno rata kapitałowa, jak i ta część raty odsetkowa mogą być wstrzymane, czyli zawieszone, jej spłacanie na ten okres, który jest określony ustawą – co oczywiście nie oznacza zupełnego zwolnienia ze spłaty kredytu, żeby nikt tego, proszę Państwa, nie mylił.
To oznacza, że trzeba będzie oczywiście spłacić te raty kredytowe, tylko trzeba będzie je spłacić później. W istocie jest to płatność odroczona.
Ale co jest ważne? Że w obecnej dla wielu rodzin, dla wielu osób trudnej sytuacji to zawieszenie spłacania kredytów daje możliwość podjęcia pewnych decyzji finansowych, majątkowych, jeżeli chodzi o gospodarkę finansową w rodzinie czy jeżeli chodzi o codzienne funkcjonowanie, przeprowadzenie pewnych przedsięwzięć. Wiecie Państwo, że różnie to bywa, więc ta możliwość dla osób, które są zainteresowane, które chcą skorzystać z tego zawieszenia spłat kredytów hipotecznych, będzie możliwa. To ważny element, wiele osób bardzo na to czeka.
Bardzo dziękuję jeszcze raz Pani Minister, Panu Ministrowi i rządowi za przygotowanie tego rozwiązania i dziękuję parlamentowi za jego przyjęcie.
To jest, proszę Państwa, ten najważniejszy element. Oczywiście dla instytucji funkcjonujących na rynku mieszkaniowym, na rynku budownictwa mieszkaniowego – ta ustawa dotyczy także kredytów udzielonych przez Bank Gospodarstwa Krajowego, ale powtarzam – dla instytucji, myślę tutaj o towarzystwach budownictwa społecznego, np. o spółdzielniach mieszkaniowych. Tam zostaje wprowadzony podobny mechanizm umożliwiający zawieszenie spłaty rat. Ale – tak jak mówię – nie dla indywidualnych odbiorców, nie dla indywidualnych właścicieli mieszkań, tylko dla instytucji, które zajmują się budową, które zajmują się rozwijaniem rynku mieszkaniowego.
Proszę Państwa, to jest kwestia najistotniejsza także w ustawie o pomocy dla kredytobiorców. Są wprowadzone zmiany precyzujące, ale powtarzam – dwa najistotniejsze elementy z punktu widzenia obecnej sytuacji, sytuacji gospodarstw domowych, naszej sytuacji, sytuacji rodzin, to jest możliwość zawieszenia spłaty kredytów hipotecznych na okresy wskazane w ustawie, po pierwsze, a po drugie, przedłużenie obowiązywania tarczy antyinflacyjnej do 31 października tego roku zgodnie z ustawą. Te ulgi w obecnej trudnej sytuacji, które mogą być przez rząd wprowadzane, są wprowadzone.
Dlaczego, proszę Państwa, ta decyzja o podpisaniu tej ustawy jest tak szybka, tak błyskawiczna? Ustawa uchwalona 7 lipca przez parlament, dosłownie – można powiedzieć – w ostatnich godzinach, jest podpisywana już dzisiaj, 14 lipca. Okres wejścia w życie przepisów ustawy od jej ogłoszenia jest 14 dni, tak zwane vacatio legis. Dlaczego tak szybki termin? Bo, proszę Państwa, łatwo policzyć. Po prostu chciałem, żeby ta ustawa weszła w życie przed końcem tego miesiąca, czyli przed, krótko mówiąc, początkiem sierpnia. Dlaczego? Dlatego, że to umożliwia wszystkim posiadaczom kredytów hipotecznych, których termin zapadalności kolejnej raty kredytu będzie w sierpniu, poczynając od 1 sierpnia do końca miesiąca, wystąpienie wcześniej, przed tym terminem zapadalności, co jest konieczne, o to, żeby właśnie móc skorzystać z tego zawieszenia spłaty kredytu.
A więc ustawa wejdzie w życie jeszcze w tym miesiącu. Jeszcze w lipcu i przez te dosłownie ostatnie dni lipca będzie możliwość złożenia wniosku o zawieszenie spłaty kredytu, o te tak zwane wakacje kredytowe. Będzie można to zrobić na różne sposoby, ale między innymi ma być także taka możliwość gwarantowana poprzez bankowość internetową. Tutaj, proszę Państwa, chcę bardzo mocno zaapelować do instytucji nadzorujących rynek finansowy, rynek bankowy, między innymi do Rzecznika Finansowego, o to, żeby zwracać uwagę na to, w jaki sposób, przede wszystkim przez banki, przez instytucje finansowe rynku finansowego jest ta ustawa realizowana. Chodzi o to, żeby rzeczywiście wszyscy kredytobiorcy hipoteczni, którzy chcą skorzystać z tych benefitów, które im ta ustawa daje, z tych swoistych ulg, które im ta ustawa daje, żeby rzeczywiście mogli w terminie skorzystać, żeby mogli skutecznie złożyć te wnioski, żeby te możliwości także poprzez pewne systemowe działania instytucji finansowych, banków, były im zagwarantowane.
Bardzo proszę, żeby instytucje nadzoru rynku finansowego, rzecznik finansowy, tej możliwości pilnowali. Apeluję o to i tego oczekuję, że dla konsumentów, dla kredytobiorców ten element będzie dopilnowany.
Szanowni Państwo, to tyle i jeszcze raz dziękuję Państwu Ministrom, dziękuję Rządowi. Cieszę się, że można było tę ustawę tak szybko podpisać i że będzie ją można tak szybko wprowadzać w życie. Jest ona dzisiaj faktycznie potrzebna. To jest oddech dla tych, którzy te kredyty hipoteczne mają, a to jest bardzo wiele rodzin w Polsce, które spłacają kredyty za mieszkania, w których zamieszkują, za domy.
Jeszcze raz chcę podkreślić, tylko kredyty udzielone w złotych polskich i proszę Państwa, wyłącznie na jedno mieszkanie czy na jeden dom, to znaczy ten, który rzeczywiście jest przez konsumenta, przez rodzinę wykorzystywany przez nich do celów mieszkalnych. Jeżeli ktoś ma pięć lokali mieszkalnych na przykład i pięć kredytów, to tylko na jeden będzie mógł dostać takie zwolnienie, jako że zakładamy oczywiście, że korzysta wyłącznie z jednego.
Proszę Państwa, to tyle. Jeszcze raz dziękuję.