




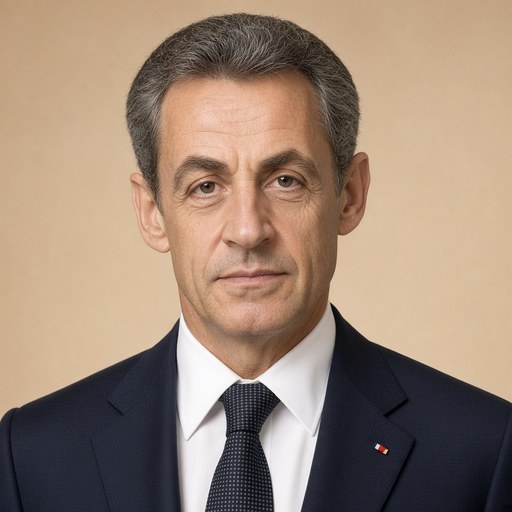
Excerpts from an interview with Mr. Nicolas Sarkozy, President of the Republic, in "Le Monde" on December 13, 2011, on measures to strengthen the Eurozone.
 Nicolas Sarkozy · President of France
- Context
- Sarkozy was interviewed by Le Monde on December 13, 2011, following the Brussels EU summit, discussing measures to strengthen and stabilize the eurozone.
- Main themes
- Eurozone crisis management, Brussels summit agreement, European economic governance, euro stability, European Stability Mechanism, sovereign debt crisis, ECB role, shared sovereignty, European integration, competitiveness and growth, banking and financial interdependence, IMF resources
- Duration
- ~24 min
- Words
- 2,910
- Sentences
- 192
- Readability
- 61
- Grade
- 8.3
- Syntax
- 2.66
- Vocabulary
- 2.20
Translated from French
This is an interview, press conference or exchange with other speakers. It is split into sentences and counted in the corpus, but its sentences are not tagged on the twelve indices.
192 sentences in 67 paragraphs
Q - On Thursday, December 8, at the congress of the European People's Party, you said that the risk of an explosion in Europe has never been so high. After the Brussels summit on Thursday and Friday, is this risk now averted?
R - I wish I could say it is completely averted. However, I will refrain from that. We have done everything that was possible to do. In a perfect, theoretical world, we should do more, but the characteristic of a statesman, of a man of government, is to work with realities. That said, this summit marks a decisive step towards European integration. In this respect, it creates the conditions for a rebound and an exit from the crisis.
The euro is the heart of Europe. If it explodes, Europe will not survive. The crisis of trust and credibility of the euro therefore posed a risk to the sustainability of the European Union.
The truth is that we had to repair the shortcomings of the euro at the time of its creation in the midst of a crisis. Thus, nothing had been planned regarding the convergence of the economic policies of the member countries of the euro. Then, some countries were welcomed into the zone when they were not prepared for it. This had the consequence of weakening the entire system, like a poisoned pill, due to the interdependence of banking and financial networks. These countries had to impose on their peoples sufferings they did not expect.
If you consider that all this took place against the backdrop of an unprecedented debt crisis in the history of the world, I did not seek to dramatize when I said that we were all on the edge of the precipice.
Q - Does the Brussels agreement address these elements of the crisis?
R - It addresses them first by creating genuine economic governance. If the economies of the zone do not converge, they cannot sustainably maintain the same currency. The fact that the responsibility for governance now lies with the heads of state and government marks an undeniable democratic progress compared to the previous situation, where everything was organized around the European Central Bank, the Commission, and the stability pact.
I add that, for the Commission, things will now be clearer. It is responsible for ensuring compliance with the treaties and for the application of sanctions. However, the one who sanctions cannot be the one who administers, at the risk of sanctioning himself. From this point of view, it is irreplaceable. Who else could do it in its place? (...)
The question posed is that of the competitiveness of our continent and the conditions for growth that must absolutely be more sustained. We will therefore have to discuss with our eurozone partners the crucial issues of industry, trade policy, the labor market, research...
Q - And, conversely, they will talk to you about taxation, public service, and pensions in France?
R - Of course. The Union is based on reciprocal compromises, built in the interest of each.
Q - Is this a transfer of sovereignty?
R - No, because we will not delegate our economic sovereignty to others. It will be a shared exercise of sovereignty by democratically elected governments. One strengthens its sovereignty and independence by exercising it with friends, allies, and partners.
I add that not a single new area of competence will be transferred to any supranational authority.
The second element is the strengthening of European solidarity, with the creation of a genuine European monetary fund, the European Stability Mechanism (ESM). This is a fund intended to assist eurozone member countries that do not have sufficient access to the market to finance their debts. This fund will be established as of July 2012 and not in July 2013. It will decide not by unanimity, but by a qualified majority of 85%. This will prevent a small minority from blocking others if they wish to move forward.
This fund will have 80 billion euros in capital, which represents a potential of 500 billion in loans. In March, we will assess whether these resources are sufficient. And, within ten days, we have committed to negotiating with our non-European partners a strengthening of the resources of the International Monetary Fund, which will further increase our firepower in the event of a crisis. The eurozone is ready to provide up to an additional 200 billion. Never have we been so ambitious in terms of solidarity.
Finally, it is the ECB that will be the operational agent of the European fund, thus increasing its credibility and effectiveness. Distrust cannot settle between these two key institutions for our financial stability.
Q - The ECB will lower its rates to 1% over three years so that banks regain margins and buy government debts. Is this moral, when it would be simpler for the ECB to lend directly to states?
R - I do not comment on the actions of the ECB. It is independent and must act within the framework of the treaties.
But the problem today, in many countries of the zone, is the tightening of credit due to fear of risk. This could lead to an economic depression. This prospect would be catastrophic. I am pleased that the ECB is providing liquidity to avoid this "credit crunch." Think of those thousands of businesses whose activity would be dramatically hindered if they did not have access to sufficient credit.
I hope that the action of the ECB, by supporting economic growth, will also help to calm unfounded fears about state debts. I trust the ECB to decide in the future the strength of its intervention.
Q - If that doesn't work, do you plan to make a large loan from individuals, like Belgium and Italy?
R - Belgium has thus raised 5.5 billion euros. The French debt is 1,692 billion euros. Each year, we borrow about 180 billion. You see that the orders of magnitude have nothing to do with what a national loan could bring.
I remind you, moreover, that we no longer have the right to give a tax advantage to state bond issues, as all those granted in the past have cost public finances dearly. Finally, it should be noted that, despite the crisis, France is currently borrowing on the markets at a historically low rate. So why should we change our strategy?
The third element of the agreement is an effort at discipline, with an inverted majority for automatic sanctions. Previously, for the Commission to sanction a defaulting state, a qualified majority in the Council was required to approve it. This will no longer be the case.
On the other hand, we did not wish for these sanctions to apply in the same way, that is to say, to be automatic, in the event of a debt overshoot in a given year. A state may be required to recapitalize a bank or a public enterprise, which will increase its public debt. We cannot hold that against it. Thus, the same causes will no longer produce the same effects. Laxity will no longer be tolerated in Europe.
Q - What is the next step?
R - In the next fifteen days, we will finalize the legal content of our agreement. The goal is to arrive at a treaty by March.
It must be understood that another Europe is being born: that of the eurozone, where the key words will be the convergence of economies, budgetary rules, and taxation. A Europe where we will work together on reforms that will allow all our countries to be more competitive, without renouncing our social model. The stability of our continent is at this price.
Q - Are you not afraid of ratification problems?
R - No, because the procedure chosen is lighter, even if each country remains master of the ratification procedure. In any case, we want to be ready by the summer of 2012. Finally, I repeat, no one will be able to contest the increased role thus given to European governments.
Q - It has been six months where the markets can still attack...
R - If you want to tell me that it is difficult, I confirm: it is difficult. No ideological framework works anymore. It takes a lot of composure not to overreact and the same composure not to underreact. I am aware of the risk of not being understood by the populations who are suffering and who see summits succeeding one another, giving the impression of being disconnected from their daily lives. At the same time, we have no choice. We must hold the course as firmly as possible and exit the spiral of crises.
Q - What do you say to those who say that the choices to stem the euro crisis are imposed by Angela Merkel?
R - To those who complain and reproach me for the Franco-German axis, I ask what they propose as an alternative strategy. Stay alone? Who can think that France alone would have advanced its ideas better? Unless someone proposes another alliance... But which one?
It is true that the Brussels summit is the result of a Franco-German compromise and, since the beginning of this crisis, we have moved towards each other. Who would have thought, two years ago, that our partners would rally to the idea of an economic government, organized around the heads of state and government? That they would subscribe to the creation of a European monetary fund, embodied by the ESM? So many French ideas! The Chancellor, whom I appreciate very much, has moved with pragmatism and intelligence.
As for the word capitulation that I have heard used by some, all this warlike language that smells of old nationalism, let me tell you what I think: I feel French to the core of my being, but my love for France has never led me to accuse our neighbors, our allies, our friends. And those who seek to foster Germanophobia discredit themselves.
Q - A triangle with the British?
R - The United Kingdom is not in the euro. The triptych Berlin-London-Paris would have made sense if we had had a crisis of the European Union, but that is not the case. It is a crisis of the euro.
Does the importance of the agreement with Germany mean that nothing can be done with London? No. We intervened in Libya with the United Kingdom, and Prime Minister David Cameron was courageous. With London, we share a commitment to nuclear energy and strong cooperation in defense, which is essential.
Q - You took time to appreciate the German model...
R - If you mean that the presidency and the confrontation with challenges change a man, that is true. If you want me to say that, after four and a half years at the Élysée, I have learned and evolved in my reasoning, that is true as well.
Between France and Germany, there is first of all history. Seventy years of confrontations followed by seventy years of peace. What should the next cycle be? We do not have the right to diverge from Germany, because divergence leads to confrontation. We must therefore understand each other and seek permanent compromises. (...)
Q - In a speech on repentance in 2006, you said that France had not committed genocide...
R - The Germans have faced their history with courage and lucidity. We have nothing to reproach them for.
Q - In Brussels last week, you put the English outside of Europe...
R - I did not see it that way. We did everything, the Chancellor and I, to ensure that the English were part of the agreement. But there are now clearly two Europes. One that wants more solidarity among its members and regulation. The other that is attached only to the logic of the single market.
Q - How did they end up alone?
R - The repeated assertion of their opposition to any prospect of entering the euro cannot be without consequence. I add that the demands regarding financial services were not acceptable. The crisis came from the deregulation of finance. We could never accept a return to the past. Europe must move towards more regulation.
Q - Is it legitimate now for the United Kingdom to remain in the single market?
R - We need Great Britain! It would be a great impoverishment to see its departure, which, fortunately, is not on the agenda. (...)
Q - Is the French president ready to accept European rules when, in 2007, you went to Luxembourg to request a postponement of France's return to balance and, recently, Prime Minister François Fillon protested against the Commission's growth forecasts?
R - We are not talking about the same time or the same world, even if it is the same president. We are all the more ready for this effort because we started it back in 2007. The implementation of the non-replacement of one civil servant for every two retiring, which earned us so much criticism, is from 2007. The reform of the judicial map is from 2008. The reform of the military map is from 2009. As for the pension reform, if we had not done it, we would be in the unenviable situation of some of our partners.
Q - How do you assess the risk of France being downgraded by financial agencies?
R - One of the three rating agencies has placed France, as well as the entire eurozone, on negative outlook. Why? Because the eurozone is facing a governance problem: this is an issue we are addressing and it is not specific to France. The second concern is the risk to French banks. The good news is that the European Banking Authority estimates the need for recapitalization of French banks at 7.7 billion euros, compared to 13 billion for Germany. Not a single cent of the state budget will therefore go to the recapitalization of banks.
The third element is the outlook for French growth. The government has set a forecast of 1% for 2012. But at the same time, a freeze of 6 billion in credits has been put in place to cope with a situation where growth is limited to 0.5%. The last point raised by the agency is the high level of our spending. But everyone recognizes that we have shown responsiveness in this area in the past.
The great risk is therefore that of the contagion of the European crisis. That is why we are fighting to control it.
Q - Are we threatened with ten years of effort or very slow growth, like Japan?
R - This is a risk that has led me not to choose a policy based on austerity. Austerity means lowering salaries and pensions. I refuse to do that and will continue to refuse. If we were to go in that direction, it would plunge France into recession and deflation. If you reduce your revenues at the same time as you cut your expenditures, you do not solve your deficit problems. That is why we decided, in 2009, on 35 billion euros in favor of future investments. This is the opposite of a policy of austerity and rigor. We need to both reduce our deficit and our debt, free up work, and regain competitiveness.
Q - But the agencies do not do us justice...
R - For now, they have maintained the triple A. If they were to withdraw it from us, we would face this situation with composure and calm. It would be an additional difficulty, but not insurmountable. What matters above all is the credibility of our economic policy and our determined strategy to reduce our expenditures. We will scrupulously respect the commitments we have made.
Q - What flagship measure should be taken to convince investors?
R - If we had not carried out the pension reform, that would be the one to implement. For the rest, there is no key or miracle measure because what matters, just as much as reducing expenditures, is increasing growth. This involves the autonomy of universities, the development of the research tax credit, future investments, and the elimination of the professional tax. Everything that France has begun to do.
Q - The golden rule?
R - The golden rule is an important measure. It is a rule of common sense: budgets must be built over several years with the aim of achieving balance. Who can in good faith contest this objective? I would have liked all French political parties to take inspiration from what the Spaniards and Germans have done by adopting this rule by consensus, without anyone losing their identity. (...)
Q - How do you analyze the growing doubt of the French about the euro?
R - The French associate the euro with their difficulties, but at the same time, they understand the risks of leaving it and isolating themselves. I pay tribute to their lucidity. The French do not contest Europe, but the way certain European policies are conducted. In this regard, trade policy is the very example of what needs to change. We increase the burdens and constraints on our producers, and we allow products made in countries that do not respect any of these constraints to enter our market. This cannot continue. Reciprocity must become the rule. Competition can only be fair; if it is unfair, we will have to draw consequences regarding the opening of our markets. ()
The original French. The tags above are read on the English translation's sentences.
Q - Jeudi 8 décembre, au congrès du Parti populaire européen, vous avez dit que jamais le risque dexplosion de lEurope navait été aussi élevé. Après le sommet de Bruxelles de jeudi et vendredi, ce risque est-il écarté ?
R - Jaimerais pouvoir dire quil est totalement écarté. Je men garderai pourtant. Nous avons fait tout ce quil était possible de faire. Dans un monde parfait, théorique, on devrait faire plus, mais la caractéristique de lhomme de gouvernement, de lhomme dÉtat, cest de faire avec les réalités. Cela étant, ce sommet marque une étape décisive vers lintégration européenne. À ce titre, il crée les conditions du rebond et de la sortie de crise.
Leuro est le cur de lEurope. Sil explose, lEurope ny résistera pas. La crise de confiance et de crédibilité de leuro faisait donc peser un risque sur la pérennité de lUnion européenne.
La vérité est quil nous a fallu réparer en pleine crise les insuffisances de leuro au moment de sa création. Ainsi, rien navait été prévu quant à la convergence des politiques économiques des pays membres de leuro. Ensuite, certains pays ont été accueillis au sein de la zone alors quils ny étaient pas préparés. Cela a eu pour conséquence de fragiliser tout le système, comme une pilule empoisonnée, en raison de linterdépendance des réseaux bancaires et financiers. Ces pays ont dû imposer à leurs peuples des souffrances auxquelles ils ne sattendaient pas.
Si vous voulez bien considérer que le tout sest déroulé sur le fond dune crise de la dette sans précédent dans lhistoire du monde, je nai nullement cherché à dramatiser lorsque jai dit que nous étions tous au bord du précipice.
Q - Laccord de Bruxelles répond-il à ces éléments de la crise ?
R - Il y répond dabord par la création dune authentique gouvernance économique. Si les économies de la zone ne convergent pas, elles ne peuvent pas conserver durablement la même monnaie. Le fait que la responsabilité de la gouvernance revienne désormais aux chefs dÉtat et de gouvernement marque un progrès démocratique incontestable par rapport à la situation précédente, où tout sorganisait autour de la Banque centrale européenne, de la Commission et du pacte de stabilité.
Jajoute que, pour la Commission, les choses seront désormais plus claires. Elle est chargée du respect des traités et de lapplication des sanctions. Or, celui qui sanctionne ne peut être celui qui administre, au risque de se sanctionner lui-même. De ce point de vue, elle est irremplaçable. Qui dautre pourrait le faire à sa place ? (...)
La question posée est celle de la compétitivité de notre continent et des conditions dune croissance qui doit absolument être plus soutenue. Nous devrons donc évoquer avec nos partenaires de la zone euro les questions cruciales de lindustrie, de la politique commerciale, du marché du travail, de la recherche...
Q - Et, réciproquement, ils vous parleront de la fiscalité, de la fonction publique et des retraites en France ?
R - Bien sûr. LUnion se fonde sur des compromis réciproques, construits dans lintérêt de chacun.
Q - Est-ce un transfert de souveraineté ?
R - Non, car on ne déléguera pas à dautres notre souveraineté économique. Il sagira dun exercice partagé de la souveraineté par des gouvernements démocratiquement élus. On conforte sa souveraineté et son indépendance en lexerçant avec ses amis, ses alliés, ses partenaires.
Jajoute que pas un seul domaine nouveau de compétences ne sera transféré à une quelconque autorité supranationale.
Le deuxième élément, cest le renforcement de la solidarité européenne, avec la création dun véritable fonds monétaire européen, le Mécanisme européen de solidarité (MES). Cest un fonds destiné à venir en aide aux pays membres de la zone euro qui nauraient pas un accès suffisant au marché pour financer leurs dettes. Ce fonds sera mis en place dès juillet 2012 et non en juillet 2013. Il décidera non plus à lunanimité, mais à la majorité qualifiée de 85 %. Cela évitera quune petite minorité puisse bloquer les autres sils souhaitaient aller de lavant.
Ce fonds aura 80 milliards deuros de capital, ce qui représente un potentiel de 500 milliards de prêts. Au mois de mars, nous examinerons si ces moyens sont suffisants. Et, dici à dix jours, nous nous sommes engagés à négocier avec nos partenaires non européens un renforcement des ressources du Fonds monétaire international, ce qui augmentera encore notre force de frappe en cas de crise. La zone euro est prête à apporter jusquà 200 milliards supplémentaires. Jamais nous navons été aussi ambitieux en termes de solidarité.
Enfin, cest la BCE qui sera lagent opérationnel du fonds européen, dont la crédibilité et lefficacité seront ainsi accrues. La méfiance ne pourra pas sinstaller entre ces deux institutions-clés pour notre stabilité financière.
Q - La BCE va baisser ses taux à 1 % sur trois ans pour que les banques retrouvent des marges et achètent des dettes dÉtat. Est-ce moral, alors quil serait plus simple que la BCE prête directement aux États ?
R - Je ne commente pas laction de la BCE. Elle est indépendante, et doit agir dans le cadre des traités.
Mais le problème, aujourdhui, dans de nombreux pays de la zone, cest le resserrement du crédit par crainte du risque. Cela pourrait conduire à une dépression économique. Cette perspective serait catastrophique. Je me réjouis que la BCE fournisse des liquidités pour éviter ce «credit crunch». Pensez à ces milliers dentreprises dont lactivité serait dramatiquement entravée si elles navaient pas accès à un crédit suffisant.
Je souhaite que laction de la BCE, en soutenant la croissance économique, contribue aussi à apaiser les craintes infondées sur les dettes des États. Je fais confiance à la BCE pour, à lavenir, décider de la force de son intervention.
Q - Si cela ne marche pas, envisagez-vous de faire un grand emprunt auprès des particuliers, comme la Belgique et lItalie ?
R - La Belgique a ainsi levé 5,5 milliards deuros. La dette française est de 1 692 milliards deuros. Chaque année, nous empruntons environ 180 milliards. Vous voyez que les ordres de grandeur nont rien à voir avec ce que pourrait rapporter un emprunt national.
Je vous rappelle, par ailleurs, que nous navons plus le droit de donner un avantage fiscal aux émissions demprunts dÉtat, tous ceux qui ont été octroyés dans le passé ayant coûté fort cher aux finances publiques. Enfin, il faut rappeler que, en dépit de la crise, la France emprunte aujourdhui sur les marchés à un taux historiquement bas. Pourquoi donc faudrait-il changer notre stratégie ?
Le troisième élément de laccord, cest un effort de discipline, avec une majorité inversée pour les sanctions automatiques. Avant, pour que la Commission sanctionne un État fautif, il fallait une majorité qualifiée au Conseil pour lapprouver. Désormais, cela ne sera plus le cas.
En revanche, nous navons pas souhaité que ces sanctions sappliquent de la même manière, cest-à-dire quelles soient automatiques, en cas de dérapage de la dette une année donnée. Un État peut être amené à recapitaliser une banque, ou une entreprise publique, ce qui augmentera sa dette publique. On ne peut lui en tenir rigueur. Ainsi les mêmes causes ne pourront plus produire les mêmes effets. Le laxisme ne sera plus de mise en Europe.
Q - Quelle est la prochaine étape ?
R - Dans les quinze prochains jours, nous mettrons au point le contenu juridique de notre accord. Lobjectif est darriver à un traité pour le mois de mars.
Il faut bien voir que cest une autre Europe qui est en train de naître : celle de la zone euro, où les maîtres mots seront la convergence des économies, des règles budgétaires, de la fiscalité. Une Europe où nous allons travailler ensemble à des réformes permettant à tous nos pays dêtre plus compétitifs, sans renoncer pour autant à notre modèle social. La stabilité de notre continent est à ce prix.
Q - Ne craignez-vous pas des problèmes de ratification ?
R - Non, car la procédure retenue est plus légère, même si chaque pays reste maître de la procédure de ratification. En tout état de cause, nous souhaitons être prêts à lété 2012. Enfin, je le répète, nul ne pourra contester le rôle accru ainsi donné aux gouvernements européens.
Q - Cela fait six mois où les marchés peuvent encore attaquer...
R - Si vous voulez me dire que cest difficile, je vous le confirme : cest difficile. Aucune grille de lecture idéologique ne fonctionne plus. Il faut beaucoup de sang-froid pour ne pas surréagir et le même sang-froid pour ne pas sous-réagir. Jai conscience du risque de ne pas être compris des populations qui souffrent et qui voient des sommets se succéder, donnant limpression dêtre déconnectés de leur vie quotidienne. En même temps, nous navons pas le choix. Il faut tenir la barre le plus solidement possible et sortir de la spirale des crises.
Q - Que répondez-vous à ceux qui disent que les choix pour enrayer la crise de leuro sont imposés par Angela Merkel ?
R - À ceux qui se plaignent et me reprochent laxe franco-allemand, je demande ce quils proposent comme stratégie alternative. Rester seuls ? Qui peut penser que la France seule aurait fait mieux avancer ses idées ? À moins quon me propose une autre alliance... Mais laquelle ?
Cest vrai que le sommet de Bruxelles est le fruit dun compromis franco-allemand et, depuis le début de cette crise, nous avons fait mouvement lun vers lautre. Qui aurait pensé, il y a deux ans, que nos partenaires se rallieraient à lidée dun gouvernement économique, organisé autour des chefs dÉtat et de gouvernement ? Quils souscriraient à la création dun fonds monétaire européen, incarné par le MES ? Autant didées françaises ! La chancelière, que japprécie beaucoup, a fait mouvement avec pragmatisme et intelligence.
Quant au mot de capitulation que jai entendu employer par certains, tout ce langage guerrier qui fleure bon le nationalisme dantan, laissez-moi vous dire ce que jen pense : je me sens français au plus profond de moi-même, mais mon amour de la France ne ma jamais conduit à accuser nos voisins, nos alliés, nos amis. Et ceux qui cherchent à nourrir la germanophobie se déconsidèrent.
Q - Un triangle avec les Britanniques ?
R - Le Royaume-Uni nest pas dans leuro. Le triptyque Berlin-Londres-Paris aurait eu un sens si nous avions eu une crise de lUnion européenne, mais ce nest pas le cas. Cest une crise de leuro.
Limportance de lentente avec lAllemagne signifie-t-elle quon ne peut rien faire avec Londres ? Non. Nous sommes intervenus en Libye avec le Royaume-Uni, et le premier ministre, David Cameron, a été courageux. Avec Londres, nous partageons lattachement à lénergie nucléaire et une coopération forte dans le domaine de la défense, qui est essentielle.
Q - Vous avez mis du temps à apprécier le modèle allemand...
R - Si vous voulez dire que la présidence et la confrontation avec les épreuves changent un homme, cest vrai. Si vous voulez me faire dire que, après quatre ans et demi à lÉlysée, jai appris et évolué dans mon raisonnement, cest vrai aussi.
Entre la France et lAllemagne, il y a dabord lhistoire. Soixante-dix ans daffrontements suivis par soixante-dix ans de paix. Quel doit être le prochain cycle ? Nous navons pas le droit de diverger avec lAllemagne, car la divergence conduit à laffrontement. Nous devons donc nous comprendre et rechercher des compromis permanents. (...)
Q - Dans un discours sur la repentance, en 2006, vous avez dit que la France, elle, navait pas commis de génocide...
R - Les Allemands ont assumé leur histoire avec courage et lucidité. Nous navons rien à leur reprocher.
Q - À Bruxelles, la semaine dernière, vous avez mis les Anglais hors dEurope...
R - Je nai pas vu les choses ainsi. Nous avons tout fait, la chancelière et moi, pour que les Anglais soient partie prenante à laccord. Mais il y a désormais clairement deux Europe. Lune qui veut davantage de solidarité entre ses membres, et de régulation. Lautre qui sattache à la seule logique du marché unique.
Q - Comment se sont-ils retrouvés seuls ?
R - Laffirmation répétée de leur opposition à toute perspective dentrer dans leuro ne peut être sans conséquence. Jajoute que les demandes sur les services financiers nétaient pas acceptables. La crise est venue de la dérégulation de la finance. Jamais nous ne pourrions accepter un retour en arrière. LEurope doit aller vers davantage de régulation.
Q - Est-il légitime, désormais, que le Royaume-Uni reste dans le marché unique ?
R - Nous avons besoin de la Grande-Bretagne ! Ce serait un grand appauvrissement de voir son départ qui, fort heureusement, nest pas dactualité. (...)
Q - Le président français est-il prêt à accepter les règles européennes alors que, en 2007, vous êtes allé à Luxembourg demander un report du retour à léquilibre de la France et que, récemment, le Premier ministre, François Fillon, a protesté contre les prévisions de croissance de la Commission ?
R - On ne parle pas de la même époque ou du même monde, même si cest le même président. Nous sommes dautant plus prêts à cet effort que nous lavons commencé dès 2007. La mise en place du non-remplacement dun fonctionnaire sur deux partant à la retraite, qui nous a valu tant de critiques, cest 2007. La réforme de la carte judiciaire, cest 2008. La réforme de la carte militaire, cest 2009. Quant à la réforme des retraites, si nous ne lavions pas faite, nous serions dans la situation peu enviable de certains de nos partenaires.
Q - Comment jugez-vous le risque de dégradation de la France par les agences financières ?
R - Lune des trois agences de notation a mis sous perspective négative la France, ainsi que toute la zone euro. Pourquoi ? Parce que la zone euro connaît un problème de gouvernance : cest un problème dont nous nous occupons et qui nest pas spécifique à la France. Deuxième souci, le risque sur les banques françaises. Bonne nouvelle : lAutorité bancaire européenne estime le besoin de recapitalisation des banques françaises à 7,7 milliards deuros, contre 13 milliards pour lAllemagne. Pas un centime du budget de lÉtat nira donc à la recapitalisation des banques.
Troisième élément, les perspectives de la croissance française. Le gouvernement a fixé une prévision de 1 % pour 2012. Mais dans le même temps, un gel de 6 milliards de crédits a été mis en place pour faire face, en cas de croissance limitée à 0,5 %. Dernier point relevé par lagence, le niveau élevé de nos dépenses. Mais chacun reconnaît que nous avons su faire preuve de réactivité en la matière dans le passé.
Le grand risque, cest donc celui de la contagion de la crise européenne. Cest pourquoi nous luttons pour la maîtriser.
Q - Sommes-nous menacés de dix ans defforts ou de croissance très lente, à la japonaise ?
R - Cest un risque qui ma conduit à ne pas choisir une politique fondée sur la rigueur. La rigueur, cest baisser les salaires et les pensions de retraite. Je my refuse et my refuserai. Si nous allions dans cette direction, cela plongerait la France dans la récession et dans la déflation. Si vous réduisez vos recettes en même temps que vous abaissez vos dépenses, vous ne résolvez pas vos problèmes de déficits. Cest la raison pour laquelle nous avons décidé, en 2009, 35 milliards deuros en faveur des investissements davenir. Cest le contraire dune politique de rigueur et daustérité. Il nous faut à la fois réduire notre déficit et notre endettement, libérer le travail et retrouver de la compétitivité.
Q - Mais les agences ne nous en rendent pas justice...
R - Pour linstant, elles ont maintenu le triple A. Si elles devaient nous le retirer, nous affronterions cette situation avec sang-froid et calme. Ce serait une difficulté de plus, mais pas insurmontable. Ce qui compte avant tout, cest la crédibilité de notre politique économique et notre stratégie déterminée de réduction de nos dépenses. Nous respecterons scrupuleusement les engagements que nous avons pris.
Q - Quelle mesure phare faut-il prendre pour convaincre les investisseurs ?
R - Si nous navions pas fait la réforme des retraites, cest celle quil faudrait faire. Pour le reste, il ny a pas de mesure clé ou miracle car ce qui compte, tout autant que de réduire les dépenses, cest daugmenter la croissance. Cela passe par lautonomie des universités, le développement du crédit impôt recherche, les investissements davenir, la suppression de la taxe professionnelle. Tout ce que la France a commencé à faire.
Q - La règle dor ?
R - La règle dor est une mesure importante. Cest une règle de bon sens : les budgets doivent être construits sur plusieurs années avec lobjectif daller vers léquilibre. Qui peut de bonne foi contester cet objectif ? Jaurais aimé que toutes les formations politiques françaises sinspirent de ce quont fait les Espagnols et les Allemands en adoptant par consensus cette règle, sans que personne ny perde son identité. (...)
Q - Comment analysez-vous le doute grandissant des Français sur leuro ?
R - Les Français associent leuro à leurs difficultés, mais en même temps, ils comprennent les risques quil y aurait à en sortir et à sisoler. Je rends hommage à leur lucidité. Les Français ne contestent pas lEurope, mais la façon dont sont conduites certaines politiques européennes. À ce titre, la politique commerciale est lexemple même de ce quil convient de changer. On augmente les charges et les contraintes sur nos producteurs, et on laisse entrer sur notre marché des produits fabriqués dans des pays qui ne respectent aucune de ces contraintes. Cela ne peut plus durer. La réciprocité doit devenir la règle. La concurrence ne peut être que loyale £ si elle est déloyale, il faudra en tirer des conséquences sur louverture de nos marchés. ().