




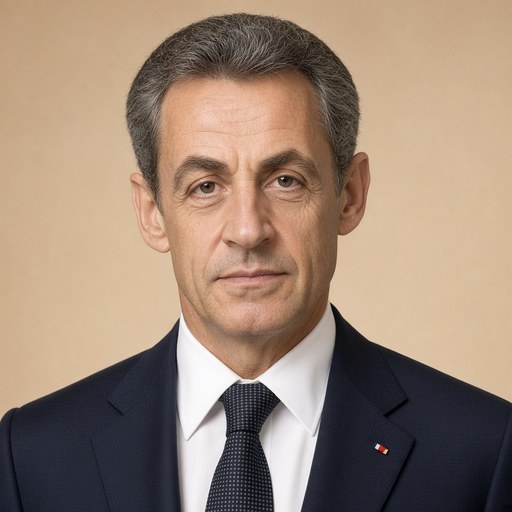
Press conference by Mr. Nicolas Sarkozy, President of the Republic, on the adoption of the Pact for the Euro, in Brussels on March 11, 2011.
 Nicolas Sarkozy · President of France
- Context
- Sarkozy addressed a Brussels press conference on March 11, 2011, following the eurozone summit that adopted the Pact for the Euro and key financial stability decisions.
- Main themes
- Pact for the Euro, eurozone economic governance, EFSF lending capacity, Greek loan terms, Irish corporate tax rate, fiscal convergence, economic policy coordination, eurozone financial stability mechanisms, common corporate tax base, Ireland loan conditions
- Duration
- ~23 min
- Words
- 2,746
- Sentences
- 138
- Readability
- 52
- Grade
- 10.7
- Syntax
- 2.87
- Vocabulary
- 2.03
Translated from French
This is an interview, press conference or exchange with other speakers. It is split into sentences and counted in the corpus, but its sentences are not tagged on the twelve indices.
138 sentences in 48 paragraphs
THE PRESIDENT - Ladies and gentlemen, good evening. We are starting a very long press conference with many questions, I hope. It is only 1:25.
You understand, this summit of heads of state and government of the euro area was very important. We have established the economic governance of Europe, as France has always requested. This economic governance is the meeting of heads of state and government, that is to say, the 17. We have adopted the Pact for the Euro, which is a decisive step. This pact will strengthen the convergence of our economic policies and the competitiveness of our economies.
We have ensured that social partners are involved in the implementation of the pact; they will be consulted annually. Furthermore, France is very pleased that the pact explicitly includes an imperative for coordination in fiscal matters. As of March 16, the Commission will make a proposal on the common corporate tax base. This is an extremely important first step to which we attach great importance.
Moreover, we have agreed on the financial capacity and flexibility of our instruments.
The first political decision is that we have agreed to increase the effective lending capacity of the mechanism known as the EFSF to 440 billion euros. As for the permanent mechanism that will succeed it in 2013, we have decided to endow it with a financial capacity of 500 billion euros. We have therefore significantly strengthened our intervention capacities.
The second decision is that we have expanded the range of usable instruments. Our two facilities - those before 2013 and those after 2013 - will mainly intervene in the form of loans, but we have decided to allow them to subscribe to bond issues in the primary market. I know this may seem technical to those who are less familiar with all this, but this little phrase may not seem like much, but it required a lot of work. This is what flexibility means, that this money can be used. Yes, I know at this hour it is a bit tedious, but still, it is very important.
The third major decision is that we have decided to align the interest rates of loans from the two mechanisms - before 2013 and after 2013 - with those of the IMF. As a result, and considering the commitments made by Greece and the excellent implementation of its program, we have decided to reduce the loans to Greece by 100 basis points and to extend the maturity of these loans to 7 and a half years. This means that Greece will repay over a longer period - it was 4 and a half years, it will now be 7 and a half years - and it will repay at a lower cost since we have decided to reduce the interest rates applied to Greece by 100 basis points.
Regarding Ireland, we have decided to revisit the conditions of its loans on March 24 and 25, because a new government has come to power and naturally, we need to continue discussions with them.
I invite you to appreciate the magnitude of the decisions we have made since May of last year. We have supported Greece and Ireland, we have created a facility of 140 billion euros, we have decided on a treaty change, we have decided to create a permanent facility, we have adopted a pact for the euro, and we have established an economic governance for the euro area.
A year and a half ago, it was not certain that we would achieve all this, but I remain at your disposal if you have questions.
QUESTION - What guarantees, or rather what allows us to believe that the corporate tax rate in Ireland will actually be increased in the coming months or years? And what was the nature of the discussions with Ireland this evening?
THE PRESIDENT - This is a very sensitive issue for our Irish friends, which I understand. It must be perfectly understood, but at the same time, all the member states of the euro area have pointed out that when we have the same currency, it is normal to converge - that convergence could not touch all areas except for fiscal convergence - that convergence first requires reflection on tax bases, if only to be able to compare them - that no one is asking Ireland to have an average rate comparable to that of Europe, but it is also difficult to ask other countries to help Ireland while Ireland responds that it intends to keep the lowest corporate tax rate in Europe. And so there is a discussion that is progressing.
I understand the problems of our Irish friends, but they must also understand the questions this raises for all the other member states of the euro area. If you look at Greece, they have lowered wages, reduced pension levels, and increased taxes. If you look at Portugal and Spain, they have done the same. All of us have had to make efforts, and Ireland, in one way or another, is certainly convinced that it will have to make them. I understand the difficulties faced by its government. There is no certainty, but there is a pact that explicitly provides for convergence, and there is a very clear demand from all the member states of the euro area for at least one gesture.
QUESTION - Mr. President, was there a specific conversation about the situation in Portugal, and if so, what were the conclusions, what message did Portugal's partners convey to it?
THE PRESIDENT - Listen, regarding Portugal, as with Greece, all the member states of the euro area wanted to express their support for the very determined, very courageous, and very effective conditions for implementing the plans in Portugal as in Greece. So it was a strong endorsement that was sent to these two governments.
QUESTION - A small clarification regarding the elements of flexibility. Does this concern both mechanisms, including for the primary market, purchases in the primary market, is it also for both mechanisms?
THE PRESIDENT - Yes. Wait, "including," you are asking me if in the primary markets, it is for both mechanisms, that is to say, to be clear: does it apply before 2013 and after 2013? It is exactly for both mechanisms, so it is immediately applicable. In case we need it, it is immediately applicable.
QUESTION - On a number of pieces of information we have heard, it seems that the exchanges with the Irish between you and Angela Merkel on one side, and the Irish on the other, were very frank, shall we say even more than that?
THE PRESIDENT - I do not know what you mean by more than frank. I have the same suit, no stigma, no, no. I greatly appreciated meeting the new Irish Prime Minister. Moreover, it did not concern only Mrs. Merkel and me, who were exactly on the same position, but the President of the Council, Herman Van Rompuy, is exactly on our position, the Spaniards, the Greeks, the Portuguese, the Austrians were exactly on the position we were. No, no, I believe there is a very strong consensus.
It is true that there are a few countries that are concerned about preserving their fiscal specificity - I think of Malta, I think of Cyprus, I think of Slovakia - that is perfectly true. But we also agree that they should keep it, but you will notice that these countries do not ask others to participate in financing their plans and that the problem for Ireland is not at all a matter of principle. It is that it is difficult to ask others to contribute to financing a plan and not to be concerned about the revenue side of that plan. This is what Mrs. Merkel and I have very courteously pointed out to the Irish Prime Minister, who also responded to us very courteously.
We still have the 24th and 25th, and as you have seen, the reduction of interest rates and the extension of the loan duration applies to Greece. To my knowledge, this does not apply to any other country; it is within the framework of a win-win agreement.
QUESTION - (inaudible)
THE PRESIDENT - We made a decision in principle. As you know, we made the decision with 17. It must be validated by the 27, but if you are waiting, does it apply right now - I mean, once the legal decision-making process on this basis has been formalized, it will be decided. The intervention in the primary markets applies before 2013 as well as after 2013, to the current mechanism as well as to the permanent mechanism.
QUESTION - So regarding the question of Irish taxes, what are the things still to be decided? What work is there to do now?
THE PRESIDENT - First of all, we should not focus solely on Irish taxes; there is an immense amount of work on fiscal convergence. And then there is something else that is extremely important, which is that all the states of the euro area have decided to work on the development of a financial transaction tax, as it is included in the euro area communiqué. We have decided to develop a project for a financial transaction tax, and I must say that France has had the determined support of Germany and Austria, in particular, regarding the perspective of this financial transaction tax. Things are progressing there as well.
QUESTION - (inaudible)
THE PRESIDENT - It has been voted. The British are not part of the euro area. I remind you that this afternoon, we were at the Eurozone Summit, the 17 of the euro area. So to my knowledge, the British are not part of it. It is the 17 of the euro area, the government of the euro area, that has decided to work on the reflection and development of a project for a financial transaction tax.
QUESTION - Mr. President, how far have you come to an agreement on two very sensitive issues: wages and pensions?
THE PRESIDENT - In the pact, things are specified. You will see the details. There is also a desire to converge, each within the framework of its national negotiations. But regarding pensions, it is: demographic question, demographic response - and regarding wages, we found a compromise with our Belgian friends to move towards an evolution of wage policy that goes in the same direction. France is no longer concerned since, to my recollection, only social benefits are indexed; wages are no longer indexed, but we have found a balance. Just as we changed the name, it is now the "Pact for the Euro in favor of competitiveness and convergence" of our economies. This has allowed us to settle the debate between those who were for convergence and those who were for competitiveness. It is now the Pact for the Euro.
QUESTION - Excuse me for wanting to do a bit of exegesis on your earlier remarks. You put Portugal and Greece on exactly the same level earlier - yet Greece is already under assistance, Portugal was not unless it is changing status?
THE PRESIDENT - Not at all, no, no, you are right to ask me the question; it avoids a misunderstanding. It is because the question that was asked of me was: what judgment do you have on the different plans of the countries in question? I was led to say that the Eurozone Council considered that the Portuguese measures, like the Greek measures, were really going in the right direction, but as you know, Portugal, to my knowledge, is not a candidate for funds from the facility. Only Ireland is. They have repeatedly said, moreover, that this would not change, but it was an assessment of the efforts that have been made, not on the modalities of financing the plan. Thank you for allowing me to clarify that.
QUESTION - (inaudible)
THE PRESIDENT - Even at this hour, I have understood the questions that should not be answered. It is up to Portugal to decide. I do not see, moreover, how - it is always what I have thought - one can force a country that would not be a candidate to emerge for a facility. It is a decision that belongs to the country. I really do not see how one could force it and on what criteria? Especially since the plan implemented by Portugal and the additional measures announced for Greece and the privatization program, for Portugal, it is in terms of budget execution. There is no problem on that side.
QUESTION - I wanted to know if the participation of China in the repurchase of debts of European countries was discussed?
THE PRESIDENT - No. We already had enough topics. The Pact for the Euro, the current facility, the future facility, frankly, we did not talk about it.
QUESTION - Just a few small clarifications on Ireland if you will, to be sure, at least for me: is it clear that Ireland agrees to discuss an evolution of its taxation, of the corporate tax base? Is Ireland specifically mentioned in the conclusions?
THE PRESIDENT - In the Pact on the Euro, it is clear since it is expressly stated. The pact having been adopted, Ireland being part of this pact, it has even been agreed that on March 16, the Commission will make a proposal. So, that is perfectly clear within the framework of the Pact for the Euro. There is no agreement between Ireland and the other countries regarding the application of the conditions of the interest rates that are its own. If there were an additional effort made on our side, we would ask for an additional effort from the other side.
QUESTION - Has it been specifically requested of Ireland to raise its corporate tax rate and has it refused?
THE PRESIDENT - It has been specifically requested of Ireland to make a gesture and, at this moment, satisfaction has not been obtained. The renegotiation of loans has been initiated and concluded for Greece but not for Ireland.
QUESTION - Are you still as firmly committed and determined not to let a Eurozone state default? That is to say, is the restructuring of public debt still firmly excluded, with the markets strongly doubting Greece's ability, in particular, to meet its obligations?
THE PRESIDENT - There is no question of allowing a Eurozone state to default. There is no question of it, we have always said it, we have always emphasized it, that would mean serious problems for the euro, we do not want that at any cost. There is no question of it. Moreover, everything that Greece is courageously and efficiently implementing shows that the problem does not arise. It is perfectly clear.
QUESTION - You mentioned the participation of social partners in the development of the pact, what form can that take?
THE PRESIDENT - It is provided in the pact that there will be a consultation every year. They will be involved in the implementation and definition of this plan and it was very important for France that the reference to European social partners be indicated, it is indicated. And here too, this has been the subject of many discussions but there is a consensus, it was very important.
QUESTION - (inaudible)
THE PRESIDENT - No. Now we have established a rule, each country will have to respect this rule. Convergence is a principle; afterwards, we have not set a timetable and standards, but it is a principle. We have committed to a pact on the euro in service of our competitiveness and the integration of our economic policy. For example, each country commits to inform the others before making an important decision. Can you imagine what problems could have been avoided if, for example, in terms of salary policies in the public service, this principle had been put into effect right from the creation of the euro? It would have avoided many unpleasant surprises for a number of countries we have just talked about. Because if you look at the curves of developments in the different public services, you see extremely divergent developments. That is what we want to avoid. There is really a sharing of information, evaluation meetings, it is really important.
With your permission, I would like to conclude this press conference.
Thank you.
Good evening and have a nice weekend.
The original French. The tags above are read on the English translation's sentences.
LE PRESIDENT - Mesdames et Messieurs, bonsoir. Nous commençons une très longue conférence de presse avec beaucoup de questions je l'espère. Il n'est jamais que 1h25.
Vous l'avez compris, ce sommet des chefs d'Etat et de gouvernement de la zone euro était très important. Nous avons mis en place le gouvernement économique de l'Europe, comme la France l'a toujours demandé. Ce gouvernement économique, c'est la réunion des chefs d'Etat et de gouvernement, c'est-à-dire les 17. Nous avons adopté le Pacte pour l'euro, c'est une étape décisive. Ce pacte renforcera la convergence de nos politiques économiques et la compétitivité de nos économies.
Nous avons obtenu que les partenaires sociaux soient associés à la mise en uvre du pacte, ils seront d'ailleurs consultés annuellement. Par ailleurs, la France est très satisfaite du fait que dans le pacte, il est prévu explicitement un impératif de coordination en matière fiscale. Dès le 16 mars, la Commission fera une proposition sur l'assiette commune de l'impôt sur les sociétés. C'est une première étape extrêmement importante à laquelle nous attachons une grande importance.
Par ailleurs, nous nous sommes mis d'accord sur la capacité financière et sur la flexibilité de nos instruments.
Première décision politique, nous nous sommes mis d'accord pour porter la capacité effective de prêts du mécanisme que l'on appelle EFSF à 440 milliards d'euros. Quant au mécanisme permanent qui lui succédera en 2013, nous avons décidé de le doter d'une capacité financière de 500 milliards d'euros. Nous avons donc renforcé de façon très significative nos capacités d'intervention.
Deuxième décision, nous avons étendu la gamme d'instruments utilisables. Nos deux facilités - celles d'avant 2013 et celle d'après 2013 - interviendront principalement sous forme de prêts, mais nous avons décidé de leur permettre de souscrire à des émissions obligataires sur le marché primaire. Je sais, cela peut paraître technique pour ceux qui sont moins familiarisés avec tout ceci, mais enfin ça n'a l'air de rien cette petite phrase, mais cela a nécessité énormément de travail. C'est cela la flexibilité, c'est que cet argent puisse être utilisé. Oui, je sais à cette heure-là, c'est un peu pénible, mais enfin quand même, c'est très important.
Troisième décision majeure, nous avons décidé d'aligner le taux d'intérêts des prêts des deux mécanismes - avant 2013 et après 2013 - sur ceux du FMI. En conséquence de quoi et compte tenu des engagements pris par la Grèce et de la mise en uvre excellente de son programme, nous avons pris la décision de réduire de 100 points de base les prêts à la Grèce et d'allonger la maturité de ces prêts à 7 ans et demi. C'est-à-dire que la Grèce va donc rembourser sur plus longtemps - c'était 4 ans et demi, ce sera sur 7 ans et demi - et elle va rembourser moins cher puisque nous avons décidé de diminuer de 100 points de base les taux d'intérêts affectés à la Grèce.
S'agissant de l'Irlande, nous avons décidé de reparler des conditions de son prêts les 24 et 25 mars, parce qu'il y a un nouveau gouvernement qui est arrivé au pouvoir et que naturellement, il faut continuer à discuter avec eux.
Je vous invite à mesurer l'ampleur des décisions que nous avons prises depuis le mois de mai de l'année dernière. Nous avons soutenu la Grèce et l'Irlande, nous avons créé une facilité de 140 milliards d'euros, nous avons décidé d'un changement de traité, nous avons décidé de la création d'une facilité permanente, nous avons adopté un pacte pour l'euro et nous nous sommes dotés d'un gouvernement économique de la zone euro.
Il y a un an et demi, il n'était pas dit que l'on arriverait à tout ceci, mais je reste à votre disposition si vous avez des questions.
QUESTION - Qu'est-ce qui garantit ou ne garantit pas mais permet de croire que le taux d'imposition sur les sociétés de l'Irlande sera réellement augmenté dans les mois ou années qui viennent ? Et quelle a été la nature des discussions avec l'Irlande dans cette soirée ?
LE PRESIDENT - C'est un sujet qui est très sensible pour nos amis Irlandais, ce que je comprends. Il faut parfaitement le comprendre mais en même temps, l'ensemble des Etats membres de la zone euro ont fait valoir que lorsque l'on a la même monnaie, il est normal de converger £ que la convergence ne pouvait pas toucher tous les domaines à l'exception de la convergence fiscale £ que la convergence passait d'abord par une réflexion sur les assiettes d'impôts, ne serait-ce que pour pouvoir les comparer £ que personne ne demande à l'Irlande d'avoir un taux moyen comparable à celui de l'Europe, mais qu'il était difficile aussi de demander aux autres pays d'aider l'Irlande et celle-ci de répondre qu'elle entendait garder l'impôt sur le bénéfice des sociétés les plus bas d'Europe. Et donc il y a une discussion qui progresse.
Je comprends les problèmes de nos amis Irlandais, mais ils doivent comprendre aussi les questions que cela pose chez la totalité des autres Etats membres de la zone euro. Si vous regardez la Grèce, ils ont baissé les salaires, baissé le niveau des pensions, augmenté les impôts. Si vous regardez le Portugal et l'Espagne, ils en ont fait de même. Tous, nous avons été amenés à faire des efforts et ces efforts, l'Irlande, d'une manière ou d'une autre, est certainement convaincue qu'elle devra les faire. Je comprends les difficultés auxquelles est confronté son gouvernement. Il n'y a pas de certitude mais il y a un pacte qui prévoit la convergence explicitement et il y a une demande très claire de l'ensemble des Etats membres de la zone euro pour qu'il y ait au moins un geste.
QUESTION - Monsieur le Président y a-t-il eu une conversation spécifique sur la situation du Portugal et si tel est le cas, quelles ont été les conclusions, quel message les partenaires du Portugal lui ont fait passer ?
LE PRESIDENT - Ecoutez, en ce qui concerne le Portugal, comme la Grèce, l'ensemble des Etats membres de la zone euro ont voulu manifester leur soutien sur les conditions très déterminées, très courageuses et très efficaces d'application des plans au Portugal comme en Grèce. C'était donc un fort satisfecit qui a été envoyé à ces deux gouvernements.
QUESTION - Une petite précision en ce qui concerne les éléments de flexibilité. Cela concerne les deux mécanismes, y compris pour le marché primaire, les achats sur le marché primaire, c'est aussi pour les deux mécanismes ?
LE PRESIDENT - Oui. Attendez « y compris », vous me demandez si sur les marchés primaires, c'est pour les deux mécanismes, c'est-à-dire pour parler clair : est-ce que c'est d'application avant 2013 et d'application après 2013 ? C'est exactement pour les deux mécanismes, donc d'application immédiate. Au cas où on en aurait besoin, c'est d'application immédiate.
QUESTION - Sur un certain nombre d'informations que l'on a entendues, il semblerait que les échanges avec les Irlandais entre vous et Angela Merkel d'une part, les Irlandais d'autre part, ont été très francs, disons même plus que ça ?
LE PRESIDENT - Je ne sais pas ce que vous appelez plus que francs. J'ai le même costume, pas de stigmate, non, non. J'ai beaucoup apprécié de découvrir le nouveau Premier ministre irlandais. D'ailleurs, cela n'a pas concerné que Madame Merkel et moi, qui étions exactement d'ailleurs sur la même position, mais le Président du Conseil Herman Van Rompuy est exactement sur notre position, les Espagnols, les Grecs, les Portugais, les Autrichiens étaient exactement sur la position que nous. Non, non, je crois qu'il y a un très grand consensus.
Il est vrai qu'il y a quelques pays qui sont soucieux de garantir leur spécificité fiscale - je pense à Malte, je pense à Chypre, je pense à la Slovaquie -, c'est parfaitement exact. Mais nous sommes d'ailleurs d'accord pour qu'ils la conservent, mais vous observerez que c'est pays ne demandent pas aux autres de participer au financement de leurs plans et que le problème pour l'Irlande n'est pas du tout un problème de principe. C'est que c'est difficile de demander aux autres de contribuer au financement d'un plan et de ne pas se préoccuper du volet recettes de ce plan. C'est ce que Madame Merkel et moi, nous avons fait valoir de façon très courtoise au Premier ministre irlandais, qui nous a répondu également de façon très courtoise.
On a encore les 24 et 25 et comme vous l'avez vu, la réduction des taux d'intérêts et l'allongement de la durée du prêt s'applique pour la Grèce. A ma connaissance cela ne s'applique pas pour un autre pays, c'est dans le cadre d'un accord gagnant-gagnant.
QUESTION - (inaudible)
LE PRESIDENT - Nous avons pris une décision de principe. Comme vous le savez, on a pris la décision à 17. Elle doit être validée par les 27, mais si vous attendez, est-ce que cela s'applique dès maintenant £ je veux dire, une fois que le processus juridique de prise de décision sur cette base-là aura été formalisé, ce sera décidé. L'intervention sur les marchés primaires s'applique avant 2013 comme après 2013, au mécanisme actuel comme au mécanisme permanent.
QUESTION - Donc la part de question des impôts irlandais, quelles sont les choses encore à décider ? Quel est le travail maintenant à faire ?
LE PRESIDENT - D'abord, il ne faut pas se focaliser, ce n'est pas forcément les impôts irlandais, il y a un travail immense de convergence fiscale. Et puis il y a quelque chose aussi qui est extrêmement important, c'est que l'ensemble des Etats de la zone euro ont décidé de travailler à l'élaboration d'une taxe sur les transactions financières, puisque c'est repris dans le communiqué de la zone euro. Nous avons décidé d'élaborer un projet de taxation des transactions financières et je dois dire que la France a eu le soutien déterminé de l'Allemagne et de l'Autriche notamment, sur la perspective de cette taxe sur les transactions financières. Les choses progressent là aussi.
QUESTION - (inaudible)
LE PRESIDENT - Ça a été voté. Les Britanniques ne font pas partie de la zone euro. Je vous rappelle que cet après-midi, nous étions en Sommet de la zone euro, les 17 de la zone euro. Donc à ma connaissance les Britanniques n'en font pas partie. Ce sont les 17 de la zone euro, gouvernement de la zone euro, qui ont donc décidé de travailler à la réflexion, à l'élaboration d'un projet de taxation sur les transactions financières.
QUESTION - Monsieur le Président, à quel point d'accord êtes-vous parvenu pour deux questions très sensibles : les salaires et les retraites ?
LE PRESIDENT - Dans le pacte, les choses sont précisées. Vous en verrez le détail. Il y a là aussi une volonté de converger, chacun, dans le cadre de ses négociations nationales. Mais sur les retraites c'est : à question démographique, réponse démographique £ et sur les salaires, on a trouvé un compromis avec nos amis Belges pour que l'on aille vers une évolution de la politique salariale qui aille plutôt dans le même sens. La France n'est plus concernée puisque dans mon souvenir, il n'y a que les allocations sociales qui sont sur l'indexation, les salaires ne le sont plus mais nous avons trouvé un équilibre. De la même façon que l'on a changé le nom, c'est « Pacte pour l'euro en faveur de la compétitivité et de la convergence » de nos économies. Cela a permis de trancher le débat entre ceux qui étaient pour la convergence et ceux qui étaient pour la compétitivité. C'est maintenant le Pacte pour l'euro.
QUESTION - Excusez-moi de vouloir faire un peu d'exégèse de vos propos de tout à l'heure. Vous avez mis exactement sur le même plan le Portugal et la Grèce tout à l'heure £ or la Grèce est déjà sous assistance, le Portugal ne l'était pas à moins qu'il soit en train de changer de statut ?
LE PRESIDENT - Pas du tout, non, non, vous faites bien de me poser la question, cela évite un malentendu. C'est parce que la question qui m'était posée était : quel jugement avez-vous porté sur les différents plans des pays en cause ? J'ai été amené à dire que le Conseil de la zone euro a considéré que les mesures portugaises comme les mesures grecques allaient vraiment dans le bon sens, mais comme vous le savez le Portugal, à ma connaissance, n'est pas candidat à des fonds de la facilité. Il n'y a que l'Irlande. Ils ont maintes fois dit, d'ailleurs, que ça ne changerait pas, mais c'était une appréciation sur les efforts qui ont été faits, pas sur les modalités de financement du plan. Merci de m'avoir permis de le préciser.
QUESTION - (inaudible)
LE PRESIDENT - Même à cette heure-là, j'ai compris les questions auxquelles il convenait de ne pas répondre. C'est au Portugal de décider. Je ne vois d'ailleurs pas - c'est toujours ce que j'ai pensé - comment on peut obliger un pays qui ne serait pas candidat à émerger à une facilité. C'est une décision qui appartient au pays. Je ne vois vraiment pas comment on pourrait le forcer et sur quel critère ? D'autant plus que le plan mis en uvre par le Portugal et les mesures supplémentaires annoncées pour la Grèce et le programme de privatisation, pour le Portugal c'est en termes d'exécution budgétaire. Il n'y a pas de problème de ce côté-là.
QUESTION - Je voulais savoir si a été évoquée la participation de la Chine dans le rachat de dettes de pays européens ?
LE PRESIDENT - Non. Nous avions déjà assez de sujets. Le Pacte pour l'euro, la facilité actuelle, la facilité future, franchement on n'en a pas parlé.
QUESTION - Juste quelques petites précisions sur l'Irlande si vous voulez bien, pour être sûr, en tous cas pour moi : est-ce qu'il est acquis, il est clair que l'Irlande accepte de discuter d'une évolution de sa fiscalité, de l'assiette sur l'impôt sur les sociétés ? Est-ce que l'Irlande est mentionnée spécifiquement dans les conclusions ?
LE PRESIDENT - Dans le Pacte sur l'euro, c'est clair puisque c'est expressis verbis ce qui est inscrit. Le pacte ayant été adopté, l'Irlande faisant partie de ce pacte £ il a même été acté que c'est le 16 mars que la Commission fera une proposition. Donc ça, c'est parfaitement clair dans le cadre du Pacte pour l'euro. Il n'y a pas d'accord entre l'Irlande et les autres pays dans le cadre de l'application des conditions des taux d'intérêts qui sont les siens. S'il y avait un effort supplémentaire fait de notre côté, on demanderait un effort supplémentaire de l'autre.
QUESTION - A-t-il été spécifiquement demandé à l'Irlande de relever son taux sur l'IS et a-t-elle refusé ?
LE PRESIDENT - Il a été spécifiquement demandé à l'Irlande de faire un geste et, à la minute où je vous parle, satisfaction n'a pas été obtenue. La renégociation des prêts a été engagée et conclue pour la Grèce mais pas pour l'Irlande.
QUESTION - Est-ce que vous êtes toujours aussi fermement engagé et déterminé à ne pas laisser un Etat de la zone euro faire défaut ? C'est-à-dire est-ce que la restructuration d'une dette publique est toujours aussi fermement exclue, les marchés doutant fortement de la possibilité pour la Grèce, notamment, de faire face à ses obligations ?
LE PRESIDENT - Il n'est pas question que l'on laisse un Etat de la zone euro faire défaut. Il n'en est pas question, nous l'avons toujours dit, nous l'avons toujours martelé, cela signifierait de graves problèmes pour l'euro, nous n'en voulons à aucun prix. Il n'en est pas question. D'ailleurs, tout ce que met en uvre la Grèce avec courage et efficience montre bien que le problème ne se pose pas. C'est parfaitement clair.
QUESTION - Vous avez évoqué la participation des partenaires sociaux à l'élaboration du pacte, quelle forme cela peut prendre ?
LE PRESIDENT - Il est prévu dans le pacte qu'il y aura une consultation chaque année. Ils seront associés à l'application et à la définition de ce plan et c'était très important pour la France que la référence aux partenaires sociaux européens soit indiquée, elle est indiquée. Et là aussi, cela a fait l'objet de nombreuses discussions mais il y a un consensus, c'était très important.
QUESTION - (inaudible)
LE PRESIDENT - Non. Maintenant on s'est doté d'une règle, chaque pays devra respecter cette règle. La convergence, c'est un principe £ après, on n'a pas fixé un calendrier et des normes, mais c'est un principe. On s'est engagé pour un pacte sur l'euro au service de notre compétitivité et de l'intégration de notre politique économique. Par exemple, chaque pays s'engage avant de prendre une décision importance à en informer les autres. Vous imaginez ce que cela aurait pu éviter comme problème si par exemple, au niveau des politiques salariales dans la fonction publique, ce principe avait été mis en vigueur dès la création de l'euro. Cela aurait évité bien des mauvaises surprises à un certain nombre de pays dont on vient de parler. Parce que si vous regardez les courbes des évolutions dans les différentes fonctions publiques, vous voyez des évolutions extrêmement divergentes. C'est cela que l'on veut éviter. Il y a vraiment une mise en commun des informations, des rendez-vous d'évaluations, vraiment c'est important.
Avec votre autorisation je mettrais bien un terme à cette conférence de presse.
Merci.
Bonne soirée et bon week-end.