




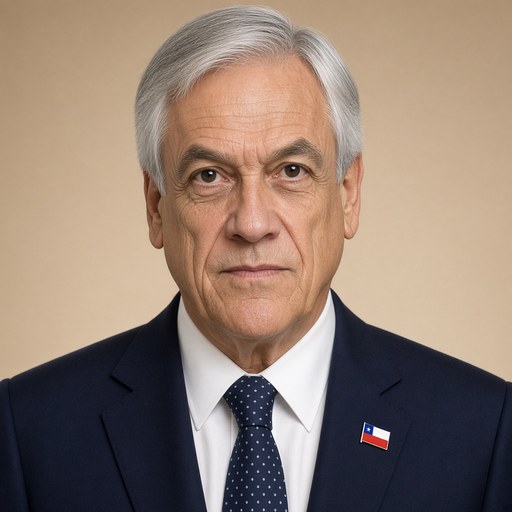
President Piñera announces improvements to the Pension System in a national broadcast.
 Sebastián Piñera · President of Chile
- Context
- Piñera addressed the Chilean nation on March 3, 2021, announcing comprehensive pension system reforms to improve retirement benefits for current and future retirees.
- Main themes
- Pension system reform, elderly welfare, solidarity pillar expansion, contributory pillar strengthening, women's pensions, middle class pension coverage, minimum pension guarantee, employer contribution increase, collective solidarity savings, pension gaps reduction, Basic Solidarity Pension, pension transparency and efficiency
- Duration
- ~11 min
- Words
- 1,337
- Sentences
- 77
- Readability
- 48
- Grade
- 10.5
- Syntax
- 2.64
- Vocabulary
- 2.42
Translated from Spanish
The broad sphere of national life a sentence belongs to. Every sentence has an Arena, so it is the denominator the other indices are read against.
Other77 sentences in 48 paragraphs
Dear compatriots, good evening:
Chile has been an ungrateful country towards its elderly. We must apply the wise principle of treating them today as we want to be treated tomorrow.
Our Government is committed to improving the quality of life for all our elderly citizens. This commitment is being realized through two major initiatives.
First, the Adult Better Program, which seeks active and healthy aging and promotes greater participation of the elderly in health, education, work, culture, sports, and greater integration into society.
And second, a broad and deep Pension Reform to improve the pensions of all retirees, both current and future, and especially the pensions of women, the middle class, and the most vulnerable sectors. Additionally, this reform aims to reduce the pension gaps between men and women and among different income groups, increase workers' participation in the management of their pension savings, and improve the transparency, efficiency, and competition of the pension industry.
This pension reform was designed in two stages:
- The first was the strengthening of the Solidarity Pillar, which allowed for a 50% improvement in the Basic Solidarity Pension (PBS) and the Solidarity Pension Contribution (APS). This reform has been in full swing since January 1, 2020, and has already benefited 1.7 million retirees, the most vulnerable in our country.
- The second stage of this Pension Reform improves the pensions of current and future retirees, and especially the pensions of women and the middle class. This reform was approved by the Chamber of Deputies in December 2019 and has since been pending in the Senate. This delay has prevented the improvement of pensions for approximately 800,000 retirees.
Second Stage of the Pension Reform
The time has come to move forward with will and urgency in this second stage of the Pension Reform. For these reasons, our Government will prioritize this Reform and will send a proposal that includes the following elements:
Strengthens and Expands the Solidarity Pillar
This reform includes the following improvements to the Solidarity Pillar:
1. It expands the coverage of the Solidarity Pillar to the middle class, increasing from the current 60% to cover 80% of the country's population. In this way, this reform addresses the need to provide social protection to 480,000 middle-class retirees who currently do not receive state support and depend solely on their individual savings.
In this way, the Solidarity Pillar will protect and benefit more than 2 million retirees, belonging to the 80% of the most vulnerable households.
2. It increases the current Basic Solidarity Pension, so that no retiree has a pension below the poverty line. This increase directly benefits more than 580,000 retirees who receive the Basic Solidarity Pension. It also improves the Solidarity Pension Contributions, benefiting more than 1 million retirees. These increases will also benefit the 480,000 people who are incorporated into the Solidarity Pillar due to its expanded coverage.
3. This Reform also anticipates the adjustment for retirees aged 65 to 74 who are beneficiaries of the Solidarity Pillar, which was due on January 1, 2022.
Strengthening the Contributory Pillar of the Pension System
This Reform also strengthens the Contributory Pillar of the Pension System by gradually increasing the employer's contribution to workers' pension savings by 6%. This additional savings will be managed by a Public Agency called the Social Security Administration Council (CASS).
Half of this increased contribution, that is, 3%, will go to a Pension Savings Account belonging to each worker. In a stable system, this additional 3% will increase the pensions of future retirees by 30%.
At the time of retirement, this Additional Pension Savings will be added to the Individual Pension Savings that each worker has in their AFP account. These savings belong to the worker, are inheritable, and will allow them to finance a higher pension.
The other half of this increased employer contribution, that is, 3%, will go to a new Collective and Solidarity Savings Program (PACS) and will finance the following benefits:
1. An immediate increase of 2.7 UF in the pension, that is, $79,135 monthly, for current female retirees over 65 years old who have contributed for at least 8 years.
2. An immediate increase of 2 UF in the pension, that is, $58,618 monthly, for current male retirees over 65 years old who have contributed for at least 12 years.
3. This pension increase will also be extended to future retirees over 65 years old.
4. To the previous benefits, an increase will be added for each year contributed in the Collective Solidarity Savings Program (PACS).
For example, a female retiree with 10 years of contributions in this new program will receive an increase in her monthly pension of $90,859 due to these improvements.
Minimum Pension Guarantee
This reform guarantees all new retirees, with 30 years of contributions and at least 10 years of contributions in the Collective Solidarity Savings Program (PACS), a pension equal to or greater than the current minimum wage, that is, UF 11.1, equivalent today to $325,330.
Severe Dependency Insurance and Subsidy
This reform includes a new Severe Dependency Insurance and Subsidy, which will provide financial support to those over 65 years old who require assistance from a third party to carry out their daily activities.
This insurance will finance an additional pension, increasing with the years of contributions and with a minimum of 3 UF monthly, that is, $87,927.
Those who do not have this new Dependency Insurance will be able to access a Dependency Subsidy, which will provide an additional benefit of between $60,000 and $80,000 monthly, to severely dependent retirees belonging to the 80% of the most vulnerable households.
Reform of the Pension Fund Administrators
Additionally, this reform incorporates greater competition, transparency, and new regulations for the Pension Fund Administrators, in order to lower commission charges and achieve greater participation of affiliates, through:
1. The creation of non-profit Pension Fund Administrators or those organized as cooperatives.
2. The possibility for administrators to distribute profits among their affiliates and offer differentiated commissions, according to tenure and size of the group that joins.
3. Greater participation of the Pension System Users Commission in the appointment of directors in the companies where pension funds are invested and the creation of Affiliate Committees in each AFP.
4. Strengthening the bidding mechanisms for the flows of new entrants to the pension system, to reduce the commissions charged.
5. The requirement that administrators with negative returns lower than a reference portfolio return refund up to 20% of the commissions charged to their users.
In addition, there is the recently approved law that allows for the early withdrawal of pension savings for terminally ill patients.
Urgency and Necessity of this Pension Reform
Dear compatriots:
We all know that this Reform is urgent and necessary. The vast majority of Chileans want their pension savings to be respected and protected, and they also want to introduce greater solidarity into our Pension System.
These citizen demands are reflected in this Reform, which not only improves the pensions of more than 2.1 million retirees, especially women, the middle class, and the most vulnerable groups, but also reduces the pension gap between men and women and among different income levels, guarantees pensions above the poverty line, and improves the future pensions of all workers.
We have had legitimate differences of opinion regarding this Reform. But these differences should never prevent us from reaching an agreement that allows us to significantly improve the pensions of more than 2.1 million people, the majority of whom are women. This Reform will also improve the future pensions of all current workers.
For all these reasons, along with deeply thanking the Senators and Ministers who have worked tirelessly to reach agreements on this matter, I want to earnestly ask that this valuable work soon transforms into an agreement that allows the Senate to approve this Reform and ensure that all our retirees, who have already waited too long, can have a life with greater dignity and opportunities.
May God bless Chile and the Chileans.
Thank you and good night.
The original Spanish. The tags above are read on the English translation's sentences.
Queridos compatriotas, muy buenas noches:
Chile ha sido un país ingrato con sus adultos mayores. Debemos aplicar el sabio principio de tratarlos hoy como queremos que nos traten a nosotros mañana.
Nuestro Gobierno tiene un compromiso con mejorar la calidad de vida de todos nuestros adultos mayores. Este compromiso se está materializando a través de dos grandes iniciativas.
Primero, el Programa Adulto Mejor, que busca un envejecimiento activo y saludable y fomenta una mayor participación de los adultos mayores en la salud, educación, trabajo, cultura, deporte y una mayor integración a la sociedad.
Y segundo, una Reforma Previsional amplia y profunda para mejorar las pensiones de todos los jubilados, actuales y futuros, y especialmente las pensiones de las mujeres, clase media y sectores más vulnerables. Adicionalmente esta reforma busca reducir las brechas de pensiones entre hombres y mujeres y entre distintos grupos de ingresos, incrementar la participación de los trabajadores en la administración de sus ahorros previsionales y mejorar la transparencia, eficiencia y competencia de la industria de pensiones.
Esta reforma previsional se diseñó en dos etapas:
- La primera fue el fortalecimiento del Pilar Solidario, que permitió mejorar la Pensión Básica Solidaria (PBS) y el Aporte Previsional Solidario (APS) en un 50%. Esta reforma está en plena marcha desde el 1° de enero del año 2020 y ya ha beneficiado a 1,7 millones de pensionados, los más vulnerables de nuestro país.
- La segunda etapa de esta Reforma Previsional mejora las pensiones de los pensionados, actuales y futuros, y muy especialmente, las pensiones de las mujeres y clase media. Esta reforma fue aprobada por la Cámara de Diputados en diciembre del año 2019 y se encuentra desde entonces en trámite en el Senado. Esta demora ha impedido mejorar las pensiones de aproximadamente 800 mil pensionados.
Segunda Etapa de la Reforma Previsional
Llegó el tiempo de avanzar con voluntad y urgencia en esta segunda etapa de la Reforma Previsional. Por estas razones nuestro Gobierno pondrá urgencia a esta Reforma y enviará una indicación que incluye los siguientes elementos:
Fortalece y Expande el Pilar Solidario
Esta reforma contempla las siguientes mejorías del Pilar Solidario:
1. Amplía la cobertura del Pilar Solidario a la clase media, pasando del actual 60% a cubrir el 80% de la población del país. De esta forma, esta reforma se hace cargo de entregar protección social a 480 mil pensionadas y pensionados de clase media, que hoy no cuentan con apoyo del Estado y sólo dependen de su ahorro individual.
De esta forma el Pilar Solidario protegerá y beneficiará a más de 2 millones de pensionados, pertenecientes al 80% de los hogares más vulnerables.
2. Aumenta la actual Pensión Básica Solidaria, para que ningún pensionado tenga una pensión bajo la línea de la pobreza. Este aumento beneficia de forma directa a los más de 580.000 pensionados que reciben la Pensión Básica Solidaria. También mejora los Aportes Previsionales Solidarios, lo que beneficia a más de 1 millón de pensionados. Estos aumentos también beneficiarán a las 480 mil personas que se incorporan al Pilar Solidario debido a su aumento de cobertura.
3. Esta Reforma también anticipa el reajuste a los pensionados de entre 65 y 74 años beneficiarios del Pilar Solidario, que correspondía el 1° de enero del 2022.
Fortalecimiento del Pilar Contributivo del Sistema de Pensiones
Esta Reforma también fortalece el Pilar Contributivo del Sistema de Pensiones, al incrementar en forma gradual en 6% el aporte del empleador al ahorro previsional de los trabajadores. Este mayor ahorro será administrado por una Agencia Pública denominada Consejo de Administración de Seguros Sociales (CASS).
La mitad de este mayor aporte, es decir un 3%, irá a una Cuenta de Ahorro Previsional perteneciente a cada trabajador. En régimen, este ahorro adicional de 3% incrementará las pensiones de los futuros pensionados en un 30%.
Al momento de pensionarse, este Ahorro Previsional Adicional se sumará al Ahorro Previsional Individual que cada trabajador tiene en su cuenta de AFP. Estos ahorros le pertenecen al trabajador, son heredables y les permitirán financiar una mayor pensión.
La otra mitad de este mayor aporte del empleador, es decir un 3%, irá a un nuevo Programa de Ahorro Colectivo y Solidario (PACS) y financiará los siguientes beneficios:
1. Aumento inmediato de 2,7 UF en la pensión, es decir, $79.135 mensuales, para las actuales pensionadas mujeres, mayores de 65 años que hayan cotizado al menos 8 años.
2. Aumento inmediato de 2 UF en la pensión, es decir, $58.618 mensuales, para los actuales pensionados hombres, mayores de 65 años que hayan cotizado al menos 12 años.
3. Este aumento de pensiones también se hará extensivo a los futuros pensionados mayores de 65 años.
4. A los beneficios anteriores se suma un incremento por cada año cotizado en el Programa de Ahorro Colectivo Solidario (PACS).
Por ejemplo, una pensionada mujer con 10 años de cotizaciones en este nuevo programa, recibirá producto de estas mejorías un incremento en su pensión mensual de $ 90.859.
Garantía de Pensión Mínima
Esta reforma garantiza a todos los nuevos pensionados, con 30 años de cotización y al menos 10 años de cotización en el Programa de Ahorro Colectivo Solidario (PACS), una pensión igual o superior al actual salario mínimo, es decir UF 11,1, equivalentes hoy a $ 325.330.-
Seguro y Subsidio de Dependencia
Esta reforma incluye un nuevo Seguro y Subsidio de Dependencia Severa, que dará apoyo económico a los mayores de 65 años que requieren ayuda de un tercero para realizar sus actividades de la vida diaria.
Este seguro financiará una pensión adicional, creciente con los años de cotización y con un mínimo de 3 UF mensual, es decir, $ 87.927.
Quienes no tengan a este nuevo Seguro de Dependencia podrán acceder a un Subsidio de Dependencia, que otorgará un beneficio adicional de entre $60 y $80 mil mensuales, a los pensionados dependientes severos que pertenezcan al 80% de los hogares más vulnerables.
Reforma a las Administradoras de Fondos de Pensiones
Adicionalmente, esta reforma incorpora mayor competencia, transparencia y nuevas regulaciones para las Administradoras de Fondos de Pensiones, de forma de bajar los cobros de comisiones y lograr una mayor participación de los afiliados, a través de:
1. La creación de Administradoras de Fondos de Pensiones sin fines de lucro u organizadas como cooperativas.
2. La posibilidad que las administradoras puedan distribuir utilidades entre sus afiliados y ofrecer comisiones diferenciadas, según permanencia y tamaño del grupo que se incorpora.
3. Una mayor participación de la Comisión de Usuarios del Sistema de Pensiones en la designación de directores en las sociedades donde se invierten los fondos previsionales y la creación de Comités de Afiliados en cada AFP.
4. El fortalecimiento de los mecanismos de licitación de los flujos de nuevos entrantes al sistema de pensiones, para reducir las comisiones cobradas.
5. El requisito que las administradoras que tengan rentabilidad negativa e inferior a la de un portafolio de referencia, devuelvan hasta un 20% las comisiones cobradas a sus usuarios.
A esto se agrega la recién aprobada ley que permite anticipar el retiro de ahorros previsionales a los enfermos terminales.
Urgencia y Necesidad de esta Reforma de Pensiones
Queridos compatriotas:
Todos sabemos que esta Reforma es urgente y necesaria. La inmensa mayoría de los chilenos quiere que se respeten y protejan sus ahorros previsionales, y quiere también, introducir mayor solidaridad a nuestro Sistema de Pensiones.
Estas demandas ciudadanas son recogidas en esta Reforma, que no sólo mejora ahora las pensiones de más de 2,1 millones de pensionados, especialmente mujeres, clase media y grupos más vulnerables, sino también reduce la brecha de pensiones entre hombres y mujeres y entre distintos niveles de ingresos, garantiza pensiones por sobre la línea de la pobreza y mejora las pensiones futuras de todos los trabajadores.
Hemos tenido legítimas diferencias de opinión respecto de esta Reforma. Pero estas diferencias nunca deben impedirnos alcanzar un acuerdo que nos permita mejorar, ahora y en forma significativa, las pensiones de más de 2,1 millones de personas, de las cuales la mayoría son mujeres. Esta Reforma mejorará también las pensiones futuras de todos los actuales trabajadores.
Por todas estas razones, junto con agradecer profundamente a los Senadores y Ministros que han trabajado intensamente para alcanzar acuerdos en esta materia, quiero pedirles encarecidamente que este valioso trabajo se transforme pronto en un acuerdo que permita al Senado aprobar esta Reforma y asegurar a todos nuestros pensionados, que ya han esperado más de la cuenta, una vida con mayor dignidad y oportunidades.
Que Dios bendiga a Chile y los chilenos.
Gracias y muy buenas noches.